China's car industry consolidation begins: who will survive?
With margins at around 3%, factories running below 50% utilisation and Toyota's two JVs set to merge, Ian Henry examines how China's overcapacity is forcing a shake-out among domestic and legacy manufacturers.
Structural change in manufacturing industries tends to happen slowly at first, then quickly when events produce tipping points. With that in mind, it seems reasonable to suggest that China is now entering a long-awaited phase of consolidation. The country’s vehicle manufacturers consist of a small number of successful domestic players and a declining number of JVs between Chinese companies and legacy manufacturers from Europe, the US, Korea and Japan.
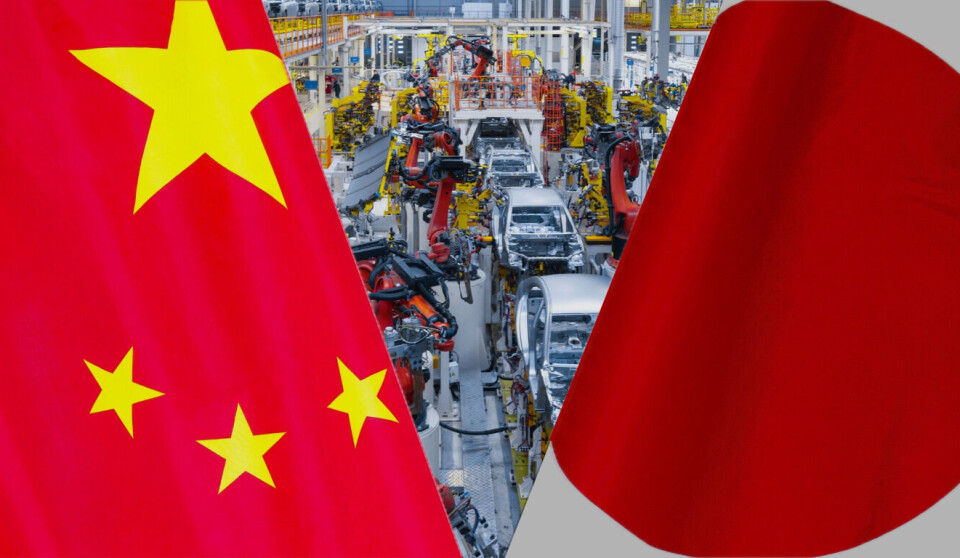
Amongst the legacy companies, who have had to operate via joint ventures owing to historic restrictions on foreign ownership of Chinese entities, the shakeout has been underway for some time
Chinese OEMs look beyond the home market
The wholly domestic brands, BYD, Chery and Geely, seem well-placed to play global roles in the long term. They may well be joined by Changan, SAIC’s MG and Xpeng, there is likely to be a fall out amongst the domestic players whose number has mushroomed in recent years. the expansion of domestic manufacturers includes companies such as Xiaomi which have entered the automotive market from the tech sector, bringing new approaches and technology to the industry in rapid fashion.
Amongst the legacy companies, who have had to operate via joint ventures owing to historic restrictions on foreign ownership of Chinese entities, the shakeout has been underway for some time. Renault, Citroen, Fiat, Renault, Mitsubishi and Mazda for example have seen their product offerings and Chinese manufacturing operations reduce and in some cases all but eliminated. For a few other legacy brands, notably Peugeot and Jeep through an arrangement with Dongfeng, some new Chinese-made models are being launched, with the aim of selling these both domestically and in export markets.

Other legacy companies, notably GM, Toyota and Volkswagen, should remain in China supplying both the domestic market and increasingly export markets as well. The futures of Honda and Nissan in China are still open to question with both brands experiencing significant falls in Chinese volumes in recent times, but without significant export volume to compensate; meanwhile, Ford will move future production for the US market back to the US at the next model change for the Lincoln Nautilus for example.
The decision for the two JVs to effectively become one in all but name has been taken at the behest of the Chinese government which can see that there are too many vehicle companies in China which operate at sub-optimal scale
Changes to JVs drive wider restructuring
However, developments at two JVs involving Toyota, one with FAW in Tianjin in the north of the country, the other with GAC at Guangzhou in the south, are significant. These could be the events which tip the industry into a wider restructuring process.
The current shareholding structures of both FAW-Toyota and GAC-Toyota JVs, in which Toyota holds 50% and the Chinese company the other 50%, are being reorganised, with Toyota’s full acceptance. The hitherto separate JVs will effectively operate as one company in future, especially with “behind the scenes” processes in purchasing and logistics especially. Details remain to be finally confirmed, but it seems likely that GAC will be the leader in whatever configuration is eventually agreed.
The development involves two previously separate partly state- and partly privately-owned entities coming together – under the direction of the Chinese government – to continue to work with – and learn from – a global leader in Toyota. This amounts to controlled or directed state capitalism in action. The decision for the two JVs to effectively become one in all but name has been taken at the behest of the Chinese government which can see that there are too many vehicle companies in China which operate at sub-optimal scale.

Negotiations are taking place on the valuations of each operation, with the outcome complicated by FAW’s 100% state-owned position and GAC’s status as a listed entity with independent shareholders. How far the central government actually wants to get involved in details of the merger remains to be seen. Public information on the details of the merger has been varied, with some reports says that GAC will acquire FAW’s 50% in the FAW-Toyota JV. Other reports have suggested that the state-owned FAW could actually end up holding between 10-20% of GAC, with GAC itself holding 25% in FAW. Such a cross-shareholding arrangement is reminiscent of the complex and somewhat convoluted arrangements of the Renault-Nissan Alliance structure. Whatever the final shape of the deal, the authorities will hope it all leads to improved local R&D, supply chains and use of manufacturing assets.
As well as being directed by the central governed, the GAC and FAW Toyota JV merger is also a case of geographic consolidation: GAC had originally been allocated the job of contributing to industrialising the south of China and FAW the same task, a few years earlier, for the north-west; now, with both entities reliant on Toyota, a merger of sorts is economically logical.
Industry consolidation and co-operation
There are other examples of industry consolidation and co-operation taking place in the name of efficiency. For example, Geely and NIO are merging their battery swapping operations; while Changan is merging two of its brands, Avatr and Deepal, in their back-office functions especially, although in their market facing operations, they will remain independent. And at Geely platforms are being used across multiple brands in the search for volume efficiency but maximum differentiation at the same time.
Geely’s approach to internal consolidation is much more substantial than Changan’s; Geely has become adept at sharing factories, platforms and distribution networks
Geely’s approach to internal consolidation is much more substantial than Changan’s; Geely has become adept at sharing factories, platforms and distribution networks. “One Geely” is its new strategy strapline which is intended to lead to “behind the scenes” resources shared across Geely, Volvo, Zeekr, Lynk&CO and Smart for example. This has been evident for some years with shared platforms such as SEA, CMA and more recently GEA, used across two or more brands, and in the case of GEA this will also be used outside the Geely group for models made at the Ford Valencia factory in which Geely is taking a 34% stake. Also, Renault is currently using the CMA platform in Korea for the Filante and Koleos models and will use the GEA platform for a new EV; Geely, it should be noted also holds 34% in Renault Korea, mirroring the situation at Ford Valencia.
The above examples all differ. One involves significant cross brand platform coordination (Geely); one involves some process coordination across brands (Changan); one involves sharing infrastructure assets (battery swapping at Geely and NIO); and the other (FAW-Toyota and FAW-GAC) involves state-owned entities being directed to merge by central government.

Challenges for car makers in the Chinese market
Why is this happening now is a question worth asking: as is the case with industry restructuring elsewhere, basic economics are at the heart of the decisions taken. Margins in the Chinese automotive manufacturing sector are currently running at 3% or so, and as low as 1.5% in some cases. The Chinese domestic market has peaked, sales are falling and exports, while growing, cannot make up the shortfall. The industry has built too much vehicle production capacity in China and as economic conditions tighten there is no realistic possibility of Chinese demand picking up to fully utilise this capacity.
At the same time the industry continues to launch new models at an alarming pace, with over 500 new vehicles or variants of existing models having been launched in China in the first half of 2026 alone. There are more than 50 companies operating in the Chinese vehicle market, with over 120 brands; something will have to give, especially with the top ten groups accounting for over 70% of production both this year and last. BYD, Geely and Chery, the top three manufacturers, accounted for 35% of production last year and this total is expected to approach 40% by the end of 2026. The tenth ranked producer, Tesla, made 850,000 cars in China last year.
Almost every company outside the top ten is expected to see failing production this year, with only GAC and Leapmotor growing. Honda, Nissan, BMW, Mercedes and domestic companies FAW and Dongfeng are all expected to see significant declines in production in China this year. The impact of this concentration is that there is limited room for the other smaller players however one looks at it. Moreover, across the market, there are overlapping products, duplicate R&D operations, underutilised factories and too many dealerships which lack scale in terms of the range offered and units sold.
However, while the changes underway appear logical, the question remains as to whether the pace of change will be sufficiently rapid or too slow to prevent some serious financial losses across the sector? It is difficult to be certain as the process of consolidation is only just beginning. To some extent the fall-out from the consolidation process will be determined by the degree to which exports can help. recent figures suggest a boom in exports, by both Chinese brands and legacy companies also using their Chinese operations for exports: Volkswagen is exporting the Lamando sedan to Mexico for example and Nissan is exporting the Frontier Pro pick-up to Mexico as well, and to Europe through a kit operation which will see assembly in Spain at the former Santana factory in Linares.
The successful domestic brands, BYD, Geely and Chery, are also increasing exports, especially of HEVs and PHEVs to Europe. But the increased tariffs on Chinese-made EVs which have already been applied in Europe may well be extended to HEVs and PHEVs, hitting exports. Europe’s tariff policy has already led to Chinese companies accelerating manufacturing plans for Europe: BYD’s plant in Hungary has started production, Chery will finally be producing vehicles in Barcelona by the end of this year and Leapmotor vehicles will soon come off the assembly line at Stellantis’ Zaragosa plant; further expansion in the UK (Chery at Nissan), Spain (MG in a new plant) and elsewhere in Europe will see the Chinese VMs’ collective presence in Europe rise, but also reduce their export potential long term.
China’s automotive manufacturing sector has a nominal capacity for 40m vehicles per year, with some analysts suggesting it could be as high as 55m. However, production this year will be c28m, against c30m last year
The export boom – which grew by more than one-third in September for example – undoubtedly helps but because of tariff and other trade policy measures in Europe, ASEAN and potentially elsewhere, it is reasonable to suggest that exports will not permanently solve the wider problem of overcapacity in China; for all the success of BYD, Chery and Geely, many Chinese factories are operating at less than 50% capacity utilisation, and some below 25%.
Low production utilisation and falling demand
China’s automotive manufacturing sector has a nominal capacity for 40m vehicles per year, with some analysts suggesting it could be as high as 55m. However, production this year will be c28m, against c30m last year. While domestic demand in 2025 totalled c23m it is currently running at less than 20m a year. Research by Bank of America suggests that 10m vehicles may be exported annually but whether that is sustainable as Chinese companies expand production in Europe and ASEAN markets, which are key export destinations, is another question entirely.

To date the number of outright failures and exits from the market by domestic companies has been limited; Hozon and Xiyue are two examples which have exited the market but elsewhere the consolidation process is moving at what might seem like glacial speed. There were talks a year or so ago, little reported outside China, regarding the idea of Dongfeng and Changan merging; however, these state-owned entities continue to plough their own furrows, and both still want to expand into Europe to reduce their reliance on the domestic market.
Survival of the fittest, most flexible, most global?

Leaving aside the speed of consolidation the next question to be asked is who will survive amongst the Chinese brands and companies? At this stage – and looking at their initial moves outside China which they will need to succeed for the companies to be successful – it would seem reasonable to expect that BYD, Chery and Geely will become long-term global players. They all already have operations outside China and in the case of Chery and Geely they have a range of brands across which they can spread development and other costs.
But who else will emerge as long-term players from China? New entrants like Xpeng and Xiaomi appear to have what it takes to succeed outside China. They are receiving strong reviews and positive market acceptance outside China even their sales volumes outside China remain low. The head of Ford, Jim Farley, has been driving a Xiaomi in the US for some time and regards it very highly. MG (originally a British brand, now owned by SAIC) may well become a second-tier player and has a new factory planned for Spain as well as some manufacturing operations in ASEAN markets. Dongfeng and Changan have been talking about major investments in Europe for several years, but nothing has happened yet and until these “second tier” Chinese companies make significant moves outside China, their dependence on the stalled Chinese market will remain and they will remain exposed to the risk of decline there as the process of consolidation accelerates.